For many Filipinos, financial needs rarely arrive one at a time. A household may be managing monthly bills when an unexpected expense comes up, while a small business owner may need extra capital to restock or keep operations moving. Having a bank account or e-wallet makes it easier to move money, but it does not always mean the right financial support is available when it is needed.
With 58% of Filipino adults now owning a formal financial account, the next challenge for financial inclusion goes beyond access and into the actual usage of services to save and borrow securely.
Reaching more people with responsible credit, for example, requires more than a single institution. Banks, fintech companies, payment networks, businesses, regulators, and industry groups each bring different strengths, from capital and technology to distribution and consumer protection.
For Tala, bringing those strengths together has become an important part of how it plans to grow and serve more customers. The AI-native credit infrastructure company is expanding partnerships within and beyond the financial industry to reach more Filipinos in line with its mission to empower the global majority and turn wider credit access into greater financial agency.
“Financial inclusion thrives when different parts of the ecosystem work together,” said Moritz Gastl, President and General Manager of Tala Philippines. “With over a decade of experience in assessing thin-file borrowers through alternative data, Tala brings real-time credit decisioning and proprietary risk intelligence to the table, while our partners bring reach, capital, and other strengths. Together, we can serve more Filipinos in ways that are practical, responsible, and relevant to how they already manage money.”
Expanding Where and How Filipinos Access Credit
Through embedded finance, Tala aims to make its proprietary credit scoring capabilities and infrastructure available to other companies so they can fund and offer credit through their own apps or networks.
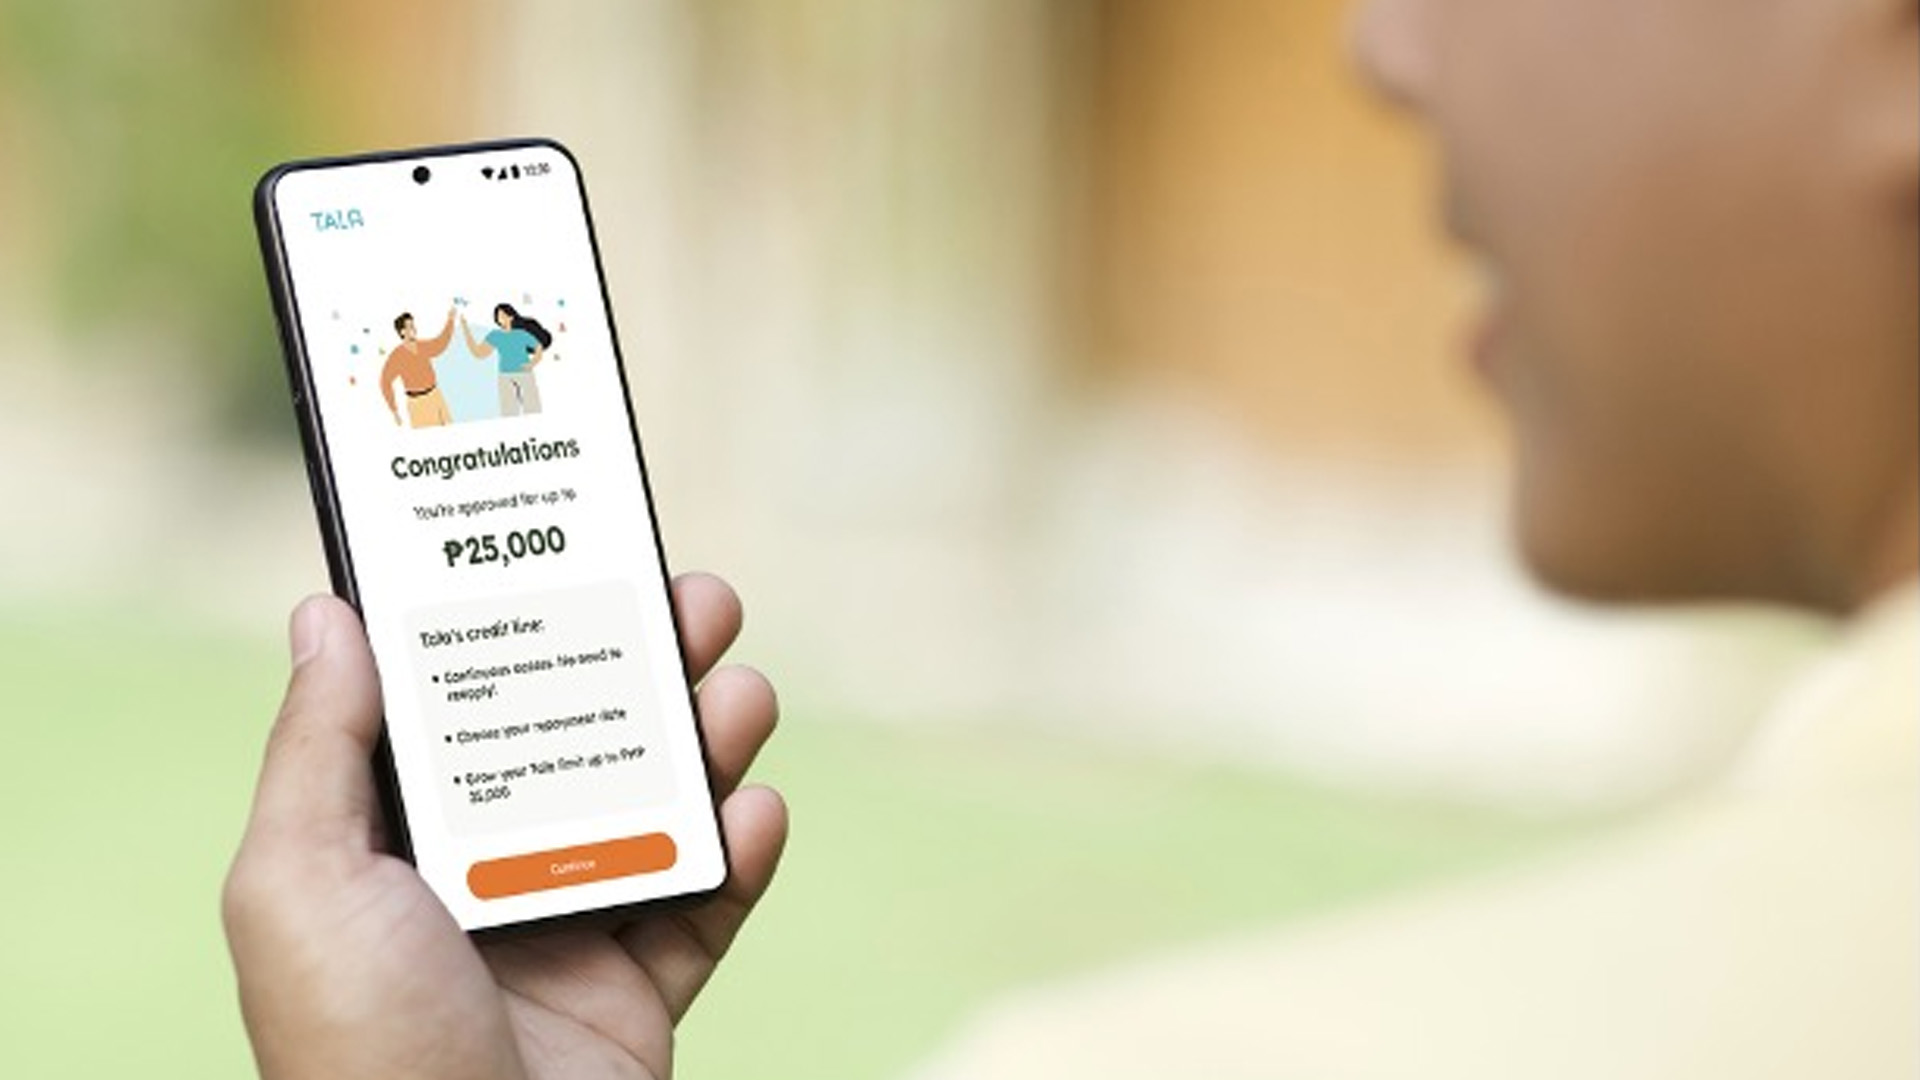
Tala offers Credit-as-a-Service, or CaaS, a plug-and-play infrastructure that businesses can integrate through lightweight APIs or an SDK, with real-time credit decisions delivered within minutes. For businesses, it offers a secure and sustainable way to provide financing without building the full underwriting infrastructure themselves. For customers, it creates another way to safely and seamlessly access credit through platforms already part of their lives, including for economically active people whose ability to repay may not be fully captured by conventional credit records.
Once approved, customers still need an easy way to access their funds. Tala’s disbursement and cash-out network connects them to e-wallets, banks, and over-the-counter payment channels, so they can receive money through services they already use. That matters because many Filipinos move between digital payments and cash depending on what they are paying for and how they manage money day to day.
Serving more customers also requires enough capital behind that credit. Through loan channeling partnerships, Tala can combine its technology and customer reach with the funding capacity of financial institutions, unlocking larger pools of capital at lower cost and expanding credit supply.
A major loan channeling partnership launched in 2024 showed how that model can work at scale, combining institutional capital with Tala’s credit infrastructure and experience serving customers with limited conventional credit histories. For customers, these arrangements largely happen behind the scenes. What matters is whether they create more opportunities to access formal credit when it is needed.
Growing Credit Access With Stronger Protections
As credit reaches more Filipinos, the protections surrounding it also have to keep pace. Through its leadership role in the Consumer Lending Association of the Philippines and engagement with other trade associations, Tala works alongside industry peers on responsible lending, consumer-centric co-regulation, anti-fraud efforts, and policies that strengthen consumer protection.
Its Debt with Dignity advocacy is part of that work. Through the Global Debt Collection with Dignity Initiative, Tala is advancing a framework that governments, regulators, and organizations can adapt to protect borrowers from abusive collection practices. Wider access should come with clear standards for how customers are treated throughout the credit journey.
Together, these relationships allow Tala to address different parts of the same challenge, from expanding where credit is available and how funds are accessed to increasing capital supply and strengthening safeguards.
For Filipinos, the value of those partnerships should ultimately be practical. Credit should be easier to reach, customers should have more choice in how they access their funds, and stronger protections should grow alongside digital finance. When those pieces work together, broader financial access can become something more meaningful: greater resilience, opportunity, and financial agency.